Step-Up SIP vs Flat SIP: How a 10% Annual Increment Drastically Accelerates Wealth Creation
## Step-Up SIP vs Flat SIP: How a 10% Annual Increment Drastically Accelerates Wealth Creation
You start a Systematic Investment Plan because you want money to grow while you work. Then years pass, your salary rises, and that same SIP amount sits frozen. That gap is the real story behind step-up SIP vs flat SIP.
A 10% annual increment is not a market trick. It is a quiet decision to let your investments grow with your income. Over 20 to 25 years, that one habit can nearly double the corpus a flat SIP would have built.
What a flat SIP actually does
A flat SIP, sometimes called a regular or fixed SIP, invests the same rupee amount every month. If you start at ₹10,000, you stay at ₹10,000 until you change it yourself.
That simplicity helps when you are beginning. You get rupee cost averaging, which means you buy more units when markets are down and fewer when they are up, without trying to time anything. It is the backbone of SIP investing in mutual funds India.
The catch is inflation and income growth. Your salary does not stay still. A frozen contribution slowly loses purchasing power, even if the plan is running exactly as designed.
What a step-up SIP changes
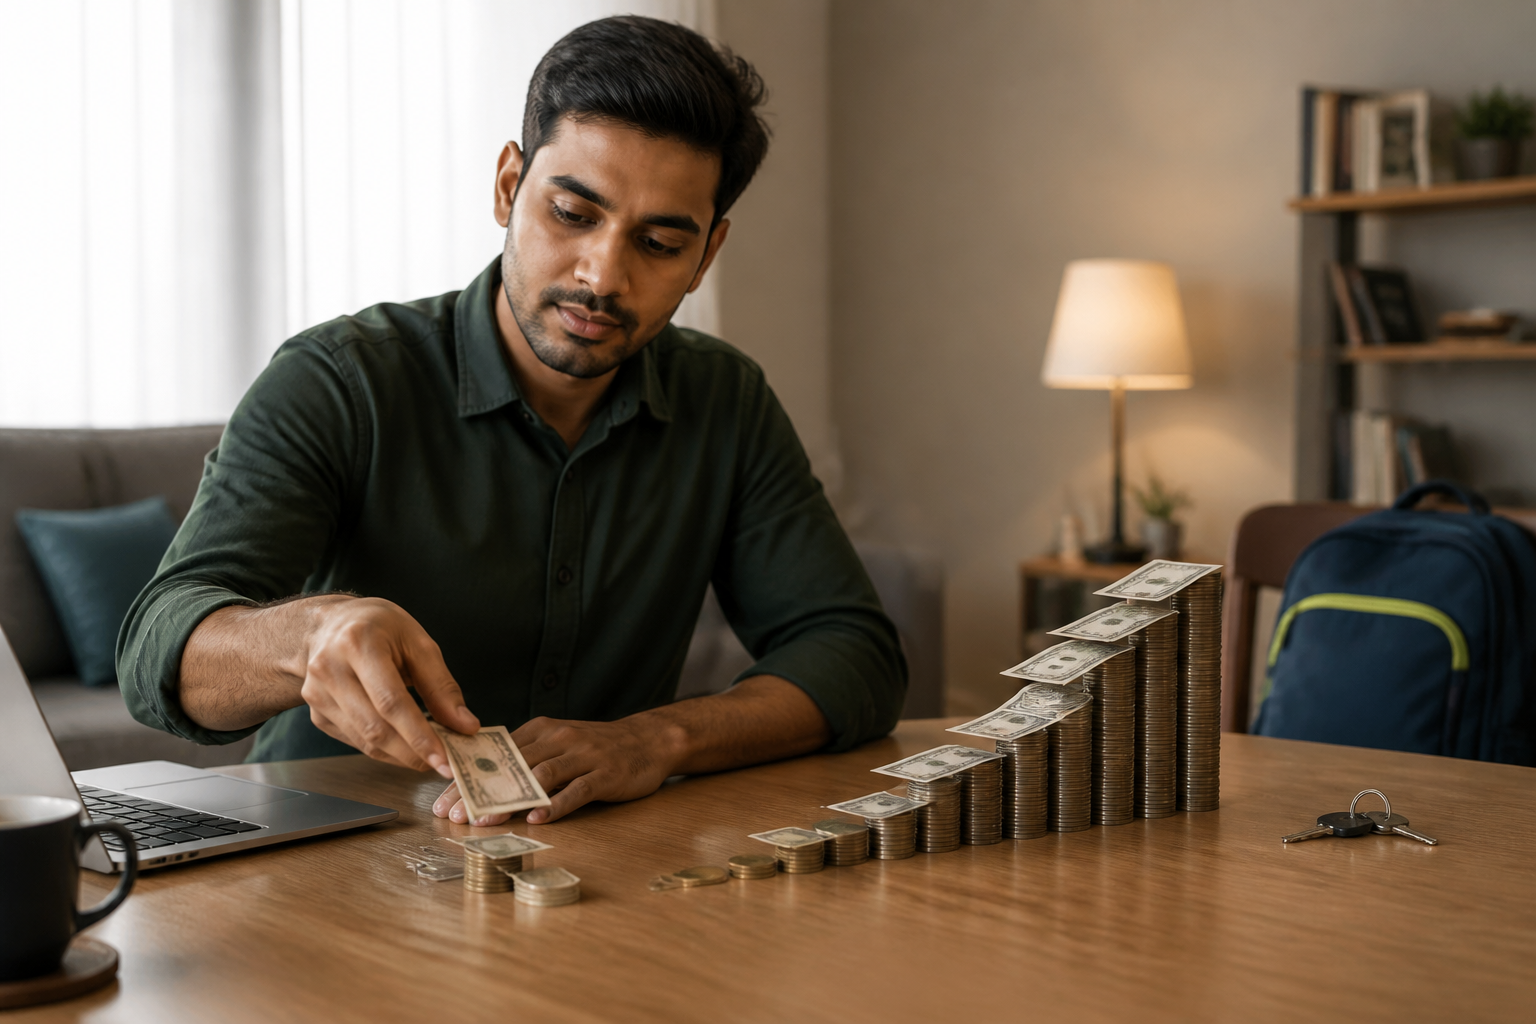
A step-up SIP (also called a top-up SIP) increases your monthly amount by a fixed percentage or a fixed rupee figure, usually once a year. Start at ₹5,000 with a 10% step-up and year two becomes ₹5,500, year three ₹6,050, and so on.
You set the instruction once. Many fund houses and apps raise the auto-debit on the anniversary date, so you do not have to remember each April.
This is financial planning that matches real life. A salaried investor in India typically sees some increment most years. A step-up SIP captures a slice of that raise before lifestyle spending claims it.
The 10% effect in rupees, not slogans
The figures below are calculator illustrations that assume around 12% CAGR. That is not a promise of future returns. Equity markets, including index funds, can have rough stretches. The comparison still holds: same return assumption, two contribution paths, a large gap.
According to financialexpress.com, a fixed SIP of ₹10,000 a month grows to about ₹2.76 crore in 25 years, while a 10% yearly step-up lifts the corpus to around ₹5.72 crore, nearly double.
Shorter horizons still show a wide spread. utilsdaily.com models a ₹5,000 start at 12% CAGR:
| Horizon | Flat SIP corpus | Step-up SIP (10% p.a.) | Extra corpus |
|---|---|---|---|
| 10 years | ₹11.5 lakh | ₹18.0 lakh | ₹6.5 lakh |
| 15 years | ₹25.0 lakh | ₹50.1 lakh | ₹25.1 lakh |
| 20 years | ₹49.9 lakh | ₹1.06 crore | ₹56.1 lakh |
You invest more in the step-up case. That is the point. Over 20 years the flat SIP puts in ₹12 lakh. The step-up path puts in about ₹34.4 lakh. The extra money works for more years, which is how wealth creation actually compounds.
rupaywise.com shows a similar pattern at ₹10,000 a month for 15 years at 12%: roughly ₹75 lakh for a regular SIP versus about ₹1.2 crore with a 10% annual step-up.
Inflation is the silent tax on a frozen SIP
India's long-term inflation has often sat near 6-7%. rupaywise.com puts it plainly: a flat ₹10,000 SIP can have the purchasing power of about ₹5,000 in 10 years and ₹2,500 in 20 years.
You are still investing. You are just investing a smaller real amount every year. A 10% step-up is a practical hedge, not because it matches inflation exactly, but because it keeps your contribution in step with a growing paycheck.
Why this fits a salaried career
At 24 you can afford ₹3,000. At 30 you earn more, but the SIP is still ₹3,000 because you never changed it. Expenses rose to fill the extra income. thesalaryinvestor.com describes this cycle well.
The step-up instruction breaks it. Your take-home rises in April. The SIP rises in the same window. You never treat that extra 10% as spending money.
A common, sustainable rate is 10%, close to typical Indian increments. If that feels tight, 5% still beats a freeze. If you get a large jump, add a one-time bump instead of raising the percentage forever.
Tie the SIP to a goal you can name: a house down payment, a child's education, a wedding fund, or a trip you actually want. Goal-based SIPs are easier to leave alone when markets wobble, because you know the date is years away.
How to start without turning it into a project
You do not need stock charts. You need a first SIP that you can keep through a lean month.
If you have not started yet, use a plain checklist: Starting your first SIP in India. Keep the first amount small enough that it never feels heroic.
Then add the step-up:
- Time it with your increment month so the extra rupees come from new income, not from an already tight budget.
- Use a 50% rule if you like numbers. If your raise is ₹5,000 a month, send ₹2,500 to the SIP.
- Automate the increase on your platform so willpower is not the plan.
- Register the bank auto-debit mandate with a high enough ceiling that later years do not fail when the amount grows. arthaengine.com suggests setting that limit well above your projected maximum.
- Review every three years, not every quarter. If salary growth lagged, lower the step-up. If it ran ahead, add a one-time increase.
thesalaryinvestor.com notes that many apps show a step-up option during SIP setup. You pick a percentage and confirm.
At TortoiseSIP the idea is the same: a set-and-forget SIP in under 10 minutes through our Rupeezy partner flow, tied to a real milestone, not a vague return target.
Pause the step-up if these are not in place
A faster SIP is not a patch for a shaky foundation.
- Build an emergency fund covering about 6 months of essential expenses in a liquid place first.
- Clear high-interest debt such as revolving credit-card balances before you accelerate equity SIPs.
- Keep money you need in 2-3 years out of equity. Use safer short-term options for near goals.
- Pick a starting SIP you could still pay through a 6-month income gap.
- Set the step-up to realistic salary growth, not a number that looks impressive on a calculator.
arthaengine.com is blunt on this, and it is good advice. Selling at market lows destroys more wealth than a slightly smaller SIP ever will. Equity belongs on a 7-10 year horizon, or longer. Match the fund type to the date you will need the money.
FAQ
Is a step-up SIP riskier than a flat SIP?
The market risk of the same fund is similar. You are simply contributing more over time. The practical risk is cash flow. If the increase outruns your salary, you may skip or redeem. Keep the percentage honest.
What if I miss a year of increments?
You can pause the step-up or keep the amount unchanged for a year. Staying invested matters more than a perfect 10% every April.
Can I step up by a fixed rupee amount instead of a percentage?
Yes. Many platforms allow either a percentage or a fixed rupee top-up. Choose the one you will actually keep.
Does rupee cost averaging still work with a rising SIP?
Yes. You still buy through ups and downs. Later years simply put more rupees to work, which is why the corpus gap widens after year 15.
How fast can I start?
If you already know your goal and a comfortable first amount, you can launch a first SIP in under 10 minutes. Browse more guides on our sitemap when you want the next article after this one.
Start the SIP. Let the 10% do the heavy lifting.
Every rupee you invest this month is a quieter future you will thank yourself for. A flat SIP is a strong start. A 10% annual step-up is how that start keeps pace with the life you are actually living.
Set the amount you can afford today. Attach it to a goal you can name. Turn on the yearly increase. Then go back to your work.
Ready to put wealth-building on autopilot? Start your first set-and-forget SIP at tortoisesip.in in under 10 minutes via our Rupeezy partner link.
3 Comments